Electronic Invoicing in the United Arab Emirates
Legal Framework, Operating Mechanism, and Compliance Deadlines
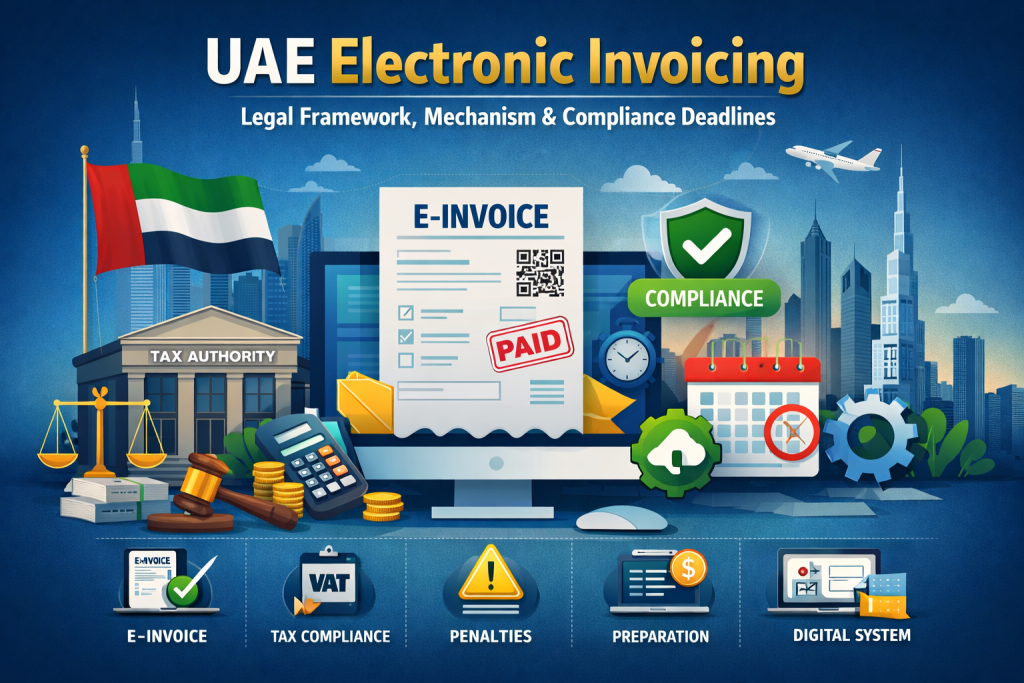
The United Arab Emirates has adopted an electronic invoicing system as a major regulatory and technological transformation aimed at fully digitizing the invoice lifecycle. This initiative enhances tax transparency, reduces errors, and increases the efficiency of Value Added Tax (VAT) compliance. More importantly, it enables effective oversight and audit processes based on structured, machine-readable data, rather than mere formal or paper-based compliance.
Legal and Regulatory Framework
The electronic invoicing system in the UAE is grounded in a comprehensive federal legislative framework that includes tax laws, tax procedures legislation, and ministerial decisions governing the accreditation of service providers. The operational model relies on approved service providers within an interoperable framework that seamlessly links commercial transactions with tax reporting.
Definition of an Electronic Invoice
An electronic invoice is not a PDF document. It is a structured digital document that is created, transmitted, and received electronically in a format that allows automated processing. This definition also applies to credit notes and includes all tax-related data required for VAT reporting and regulatory compliance.
System Operating Mechanism
The electronic invoice follows an integrated lifecycle that begins with its creation in a structured digital format containing mandatory data fields. The invoice is then validated through an approved service provider, reported to the Federal Tax Authority, delivered electronically to the buyer, and finally stored securely in digital form within the UAE in accordance with statutory record-retention requirements.
Time-Based Obligations
Taxable persons are required to issue and transmit electronic invoices or credit notes within 14 days from the date of the business transaction, along with reporting to the Federal Tax Authority within the prescribed timelines. In the event of technical failures, the Authority must be notified within two business days.
Mandatory Implementation Timeline
The implementation of the electronic invoicing system will take place in phases, beginning with contracting an approved service provider followed by mandatory application. Large enterprises will be required to comply starting in January 2027, small and medium-sized enterprises in July 2027, and government entities in October 2027. Contracting deadlines will vary depending on the entity category.
Role of Approved Service Providers
Approved service providers play a central role in the electronic invoicing system, not only from a technical standpoint but also from a legal and operational perspective. They ensure data standardization and interoperability between trading partners in accordance with approved national standards.
Accounting, Tax Impact, and Readiness
The system requires a fundamental shift from document-based accounting to data-driven accounting processes. This necessitates an assessment of ERP system readiness, tax data governance, timing controls, and the establishment of compliant in-country archiving policies. It also requires clear business continuity plans and structured procedures for managing technical disruptions.